Use this free mortgage overpayment calculator to compare your current repayment plan with an extra £50 or £100 a month, a one-off lump sum, or both. See illustrative changes to total interest and the time needed to repay your mortgage. Switch region to use your local currency.
Switching region updates the currency and typical starting figures. For UK mortgages, check your own lender’s overpayment allowance and any early repayment charges; the figures here are illustrations, not personalised advice.
Life Figured — lifefigured.com
Mortgage overpayment
Enter your current mortgage details, then add a monthly overpayment, a one-off lump sum, or both.
UK mortgages typically let you overpay up to 10% of the outstanding balance per year without an early repayment charge — this varies by lender, so check your own mortgage terms. Based on your numbers, your first-year overpayment is —, against an estimated allowance of — (—).
Free download
Want to turn this into a full plan? Grab the free Budgeting Checklist — a checklist plus 3 worksheets to put these numbers to work.
What could an extra £50, £100 or £200 a month change?
Take a hypothetical £200,000 repayment mortgage, with 25 years remaining and a 5% annual interest rate fixed for the entire term. The standard repayment would be about £1,169 a month, and total interest without overpayments would be approximately £150,754.
Extra monthly payment
Illustrative interest saved
Illustrative time saved
£50/month
About £13,415
About 1 years 11 months
£100/month
About £24,505
About 3 years 6 months
£200/month
About £41,843
About 6 years 2 months
Figures are rounded and assume monthly interest calculations, no fees, unchanged rates, and that regular payments stay the same so overpayments shorten the term. Real UK mortgage products often have shorter fixed-rate periods, overpayment limits or early repayment charges. Results are illustrative, not a forecast.
Check your lender's overpayment rules first
Some lenders allow a limited amount of penalty-free overpayments; others apply early repayment charges or reduce your monthly instalment rather than shortening the term. Check your mortgage offer and the lender's current policy. For a different balance, rate or term, use the calculator above instead of relying on this example.
Use the mortgage overpayment calculator to compare your existing repayment schedule with a scenario where you pay extra each month, make a lump-sum payment, or both. The results show illustrative interest and time differences, not a recommendation to overpay.
How the comparison works
Enter the outstanding mortgage balance, interest rate and remaining term. The calculator estimates a standard repayment schedule, then models your additional payments against that baseline. Change one input at a time to see what drives the result.
What can change the outcome?
Actual savings depend on how your lender applies overpayments, future interest-rate changes, mortgage product terms and any early repayment charges. Check whether extra payments reduce your term, monthly payment or both.
Common questions
Is it better to overpay monthly or make a lump sum?
Both approaches can change the interest charged. Timing matters: an earlier reduction in principal may have a different effect from later payments. Compare both scenarios using the inputs above.
Can I overpay my mortgage without a charge?
Some products have penalty-free allowances; others impose restrictions or early repayment charges. Check your lender's current terms rather than relying on a universal percentage.
Does overpaying always shorten the mortgage term?
Not necessarily. Your lender may recalculate monthly payments instead of reducing the term. The calculator models a particular repayment approach and your lender's treatment may differ.
Illustrative calculations assume the entered rate and repayment approach. This is educational information, not a personal recommendation.
UK MORTGAGE GUIDE
How much could you save by overpaying your mortgage?
Use this UK mortgage overpayment calculator to compare an extra monthly payment with a one-off lump sum. For example, try £50 or £100 extra each month and review the illustrative interest and repayment-term difference. Check your lender’s annual overpayment allowance and any early repayment charges before acting.
Extra mortgage payments can reduce the outstanding balance on a repayment mortgage. Depending on your lender's rules, this may reduce future interest, shorten the term, lower regular payments, or a combination. Use the calculator above to explore hypothetical monthly and one-off overpayments.
Monthly overpayments
Try an additional £50, £100 or £200 per month, then compare the estimated repayment dates and total interest. These are illustrations, not guaranteed savings: actual outcomes depend on the rate and how your lender processes the extra payments.
One-off lump sums
Explore what happens when a one-off amount reduces your balance. Before paying, check any overpayment allowance, early repayment charges, and whether you need to tell your lender how you want the payment applied.
What to check before making an overpayment
Consider your emergency savings, other borrowing, your mortgage terms and the possibility that your interest rate may change. Paying extra into a mortgage can reduce access to that money, so the calculation alone cannot tell you whether overpaying is right for you.
Free shareable resource
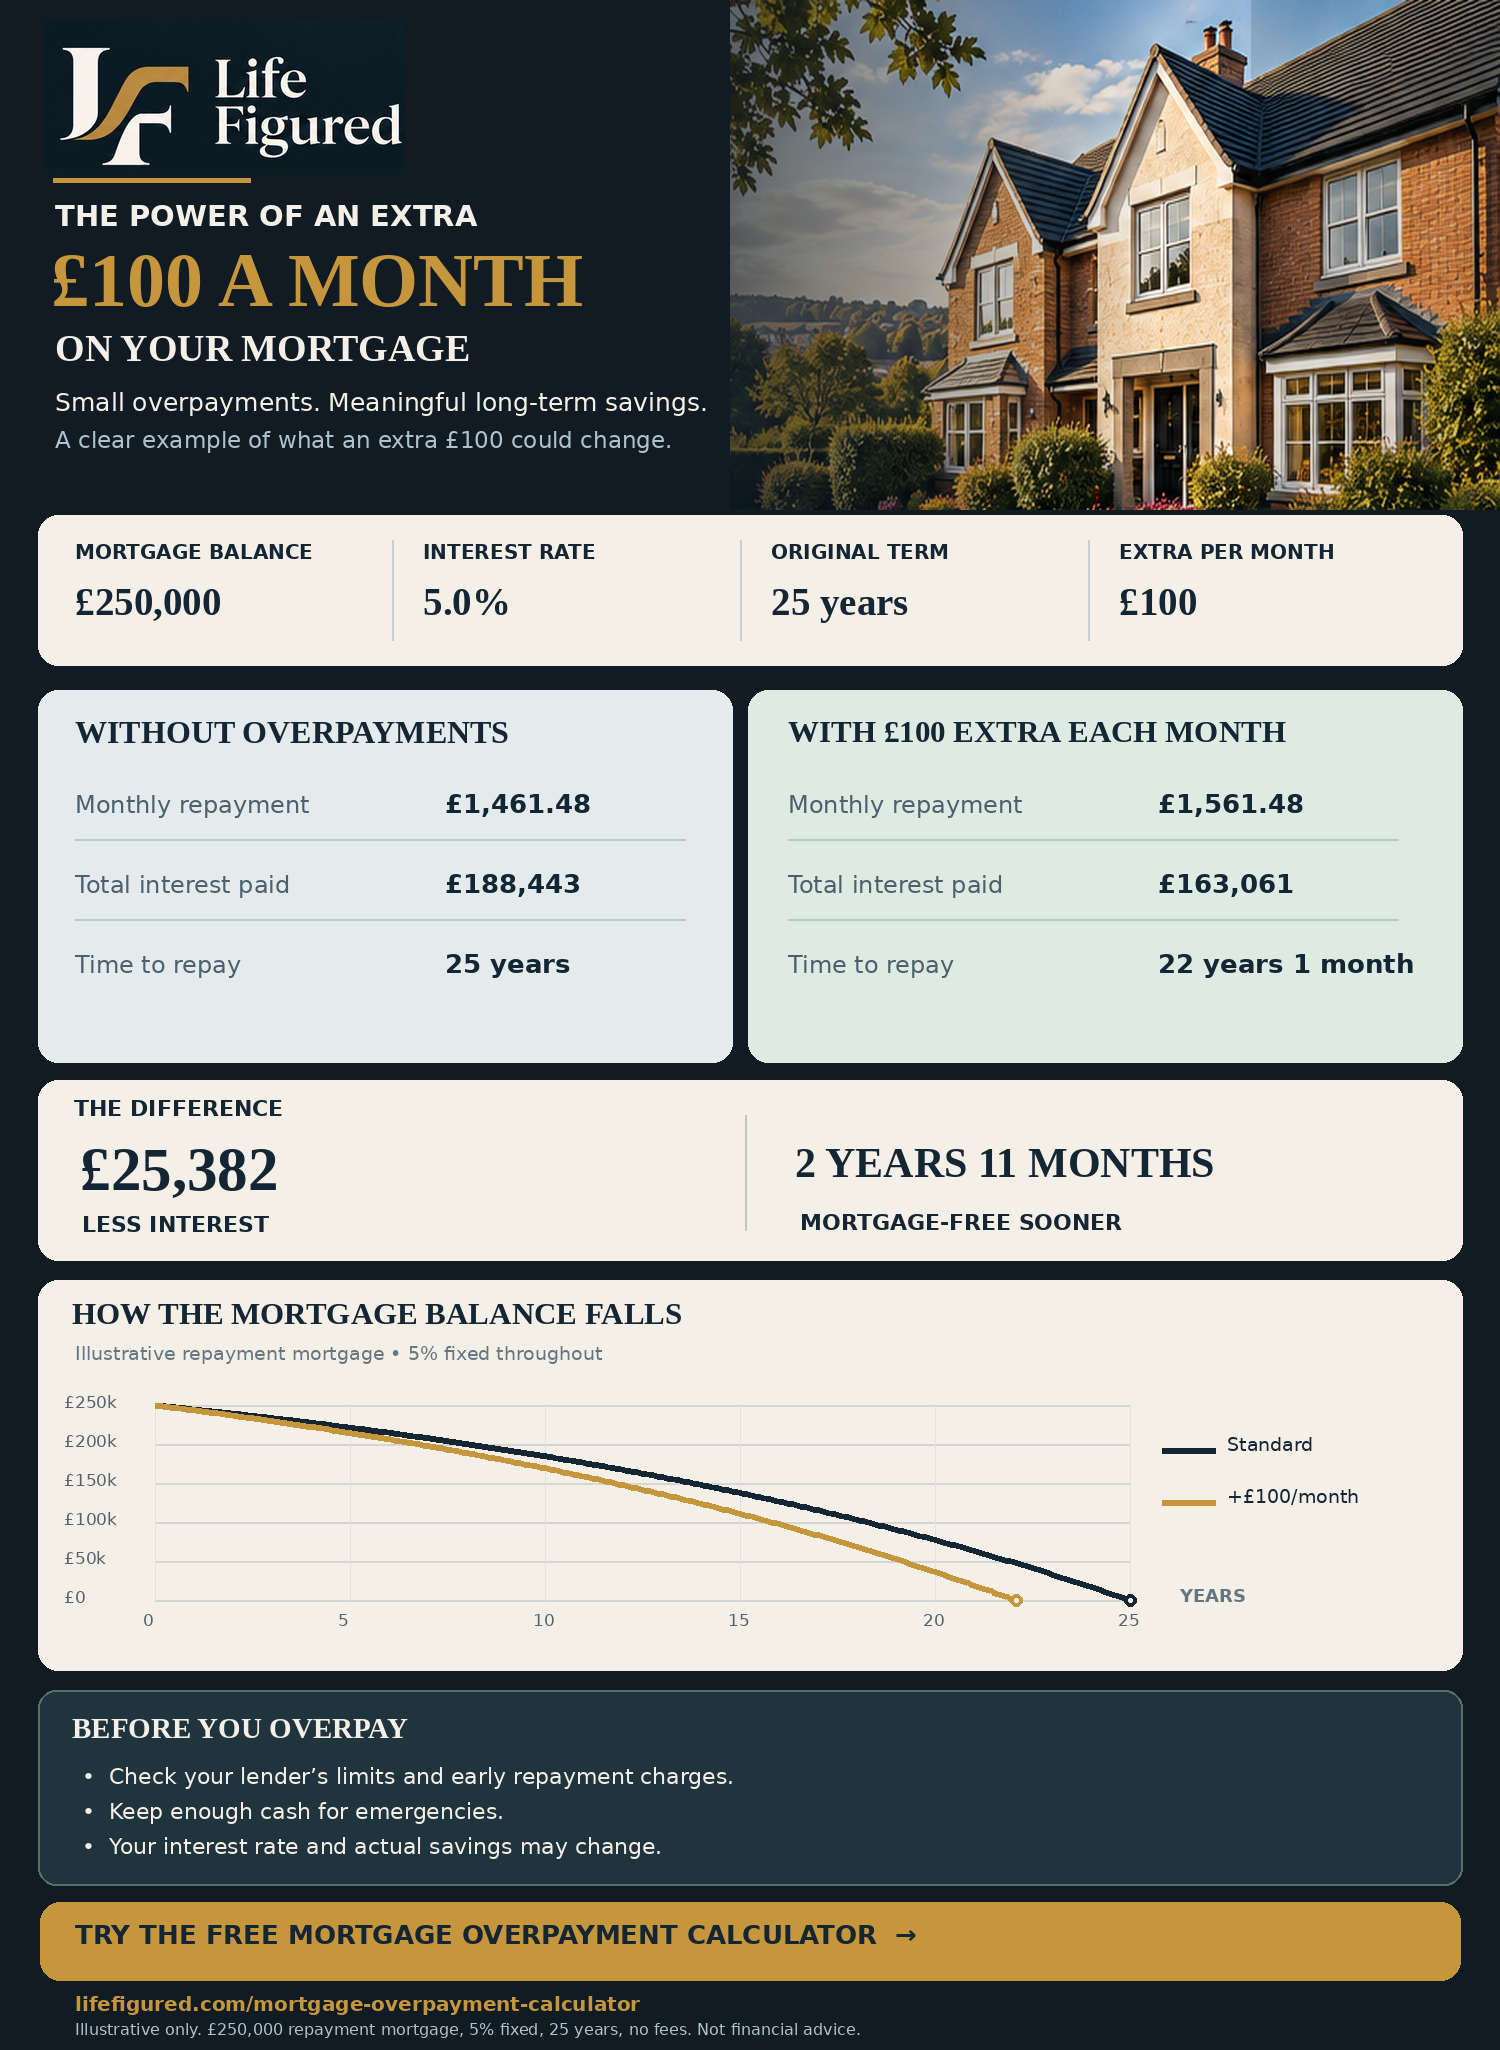
What difference could £100 extra a month make?
See the numbers in our free mortgage overpayment infographic. Download it or embed it on your website with attribution.
How to interpret your mortgage overpayment results
The calculator compares an illustrative repayment schedule with extra monthly or lump-sum payments using the figures you enter. Savings are estimates, not guaranteed outcomes or a recommendation to overpay. Your lender may set annual overpayment limits or charge early-repayment fees; changes to rates, fees or repayment arrangements can change the outcome.
Prepared by Adam, founder of Life Figured · Educational explanation reviewed for clarity October 2026 · Not personalised financial advice.
Independent background reading: MoneyHelper — buying a home · FCA — mortgages. These links are provided for further reading, not as endorsements or verification of this calculator.
It depends on your mortgage terms, interest rate, other debts, emergency savings and alternatives for your money. Overpayments can reduce future interest and the outstanding balance, but early repayment charges, overpayment limits and how your lender applies payments may affect the result. These calculations are illustrative, not a recommendation to overpay.
Will my lender let me overpay?
Most mortgages allow some overpayment each year without penalty, but many cap it (e.g. 10% of the balance annually) — check your mortgage terms before making large lump sums.
Does overpaying reduce my monthly payment or the term?
That depends on your lender — some let you choose, but by default most fixed-rate mortgages keep your payment the same and simply shorten the term.
What's better — a lump sum or regular extra payments?
Both save interest by reducing the balance you're charged on sooner. A lump sum paid earlier saves slightly more since it reduces the balance for longer, but consistent extra payments are often easier to sustain month to month.
Understanding the mortgage overpayment comparison
An overpayment can reduce the outstanding balance and therefore future interest, but actual savings depend on your interest rate, loan terms, fees and how the lender applies extra payments. Compare several scenarios and check whether your mortgage has overpayment limits or early repayment charges.
External websites open in a new tab. Life Figured is independent and is not affiliated with, approved or endorsed by these organisations. Check current rules directly with the source.
Free download
Take the guesswork out of your budget
Grab the free Budgeting Checklist below — a checklist plus 3 fill-in worksheets, delivered straight to your inbox.
Get the free budgeting checklist
A checklist plus three worksheets to get your money in order, sent straight to your inbox. Occasional new calculators and money tips after that — nothing more.
Thank you!
You have successfully joined our subscriber list.
TRANSPARENT CALCULATIONS
How we calculate this
Compares a scheduled repayment with a higher payment to estimate interest and term savings using an amortising-loan model. Check lender overpayment limits and early-repayment charges.
Methodology note added October 2026 · Prepared by Adam, founder of Life Figured · General educational estimates, not personalised financial advice. Rates and thresholds should be checked with official sources before making decisions.
We use cookies for site analytics, to understand how the calculators are used and improve them. See our privacy policy.